Newsletter
What Is a 1031 Exchange? A Plain Language Guide for Real Estate Investors
If you own real estate for business or investment, a 1031 exchange may allow you to replace it with another qualifying property while deferring taxes on the gain. Named after Section 1031 of the Internal Revenue Code, this strategy postpones tax rather than erasing it, provided the transaction meets federal requirements.
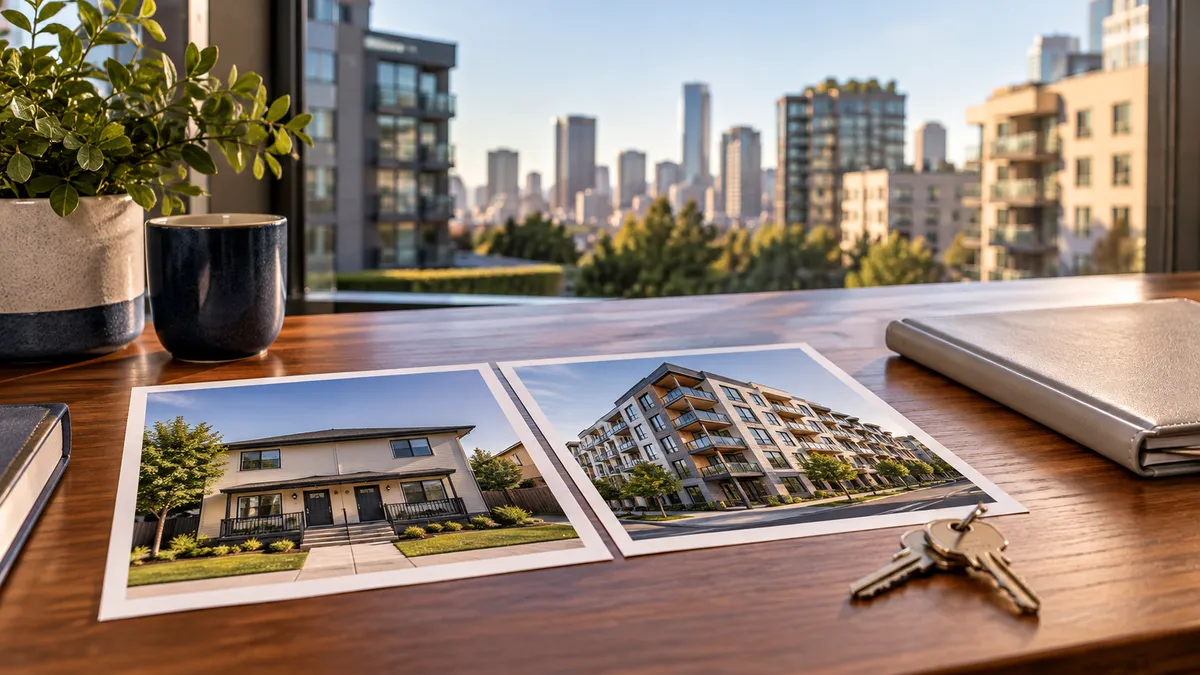
“Like-kind” does not mean the properties must be identical. For example, a rental house could be exchanged for an apartment building, or an apartment building for undeveloped investment land. Both properties generally must be held for business or investment, and U.S. real estate must be exchanged for other U.S. real estate. These examples illustrate the flexibility of the rule; the exchange still must meet all applicable requirements.
It Is More Than Selling and Buying Again
A 1031 exchange requires planning before the sale closes. Selling an investment property, depositing the proceeds into your bank account, and later using that money to buy another property generally does not qualify. In a delayed exchange, a qualified intermediary commonly coordinates the exchange, holds the proceeds, and applies them toward the replacement property under a written exchange agreement. These arrangements must be in place before the property being sold—called the “relinquished property”—transfers.
For example, suppose you sell a rental house and plan to purchase a small apartment building. Before the rental house closes, you establish the exchange with a qualified intermediary. At closing, the exchange proceeds go to the intermediary rather than to you. The intermediary then uses those funds toward the apartment building purchase. This structure may allow tax deferral, provided the properties, deadlines, and other exchange requirements are satisfied.
By comparison, if the proceeds go into your personal bank account, you have received the money directly, known as “actual receipt.” “Constructive receipt” can occur when the money is available for you to withdraw or control, even if you never spend it. Simply leaving the funds untouched does not preserve the exchange. Buying another investment property afterward generally cannot undo that receipt, which is why the exchange must be arranged before closing.
What Happens to the Deferred Gain?
A successful 1031 exchange generally carries tax consequences forward rather than making them disappear. The deferred gain is reflected in the replacement property’s adjusted tax basis—the amount used to calculate gain or loss when that property is eventually sold. This means the replacement property’s basis is not necessarily its purchase price.
For example, assume an investment property has an adjusted tax basis of $300,000 and is exchanged for another property worth $500,000. In a fully qualifying exchange, the $200,000 gain may be deferred, and the replacement property would generally retain a $300,000 basis. If that property is later sold for $600,000 in a taxable sale, the gain would be $300,000—including the gain deferred from the earlier exchange. This simplified example leaves out debt, transaction costs, and later basis adjustments, such as depreciation or improvements.
An exchange can also defer some gain while making another portion taxable now. For instance, if you receive $25,000 in cash as part of an otherwise qualifying exchange, that cash—often called “boot”—generally creates taxable gain up to the amount of gain realized. Receiving non-like-kind property or having a net reduction in debt can also affect the calculation. The key point is that completing an exchange does not automatically mean every part of the transaction is tax-deferred.
Why Ownership Structure Matters
The taxpayer that transfers the original property generally must also be the taxpayer that acquires the replacement property. This makes ownership structure an important part of planning a 1031 exchange. For example, if you own a rental house personally, buying the replacement property through a partnership you co-own with other investors generally would not satisfy this requirement. A single-member LLC treated as a “disregarded entity” for federal income tax purposes may be different because the IRS generally treats its property as belonging to its owner. The entity’s tax classification matters, not simply the name on the deed.
This distinction is especially important with real estate syndications. In a typical syndication organized as an LLC taxed as a partnership, investors own interests in the LLC, while the LLC owns the real estate. For example, selling your personally owned rental house and using the proceeds to purchase a $100,000 interest in an apartment syndication generally would not qualify as a personal 1031 exchange—even though the syndication invests in real estate. Similarly, selling your existing partnership interest generally does not qualify. The partnership itself, however, may be able to exchange real estate it owns for replacement real estate at the entity level.
Certain specialized structures can receive different treatment. An interest in a properly structured Delaware Statutory Trust (DST), for example, may qualify as replacement real estate when it meets the applicable IRS requirements. That does not mean every trust or passive real estate investment qualifies. Before committing exchange funds, investors should have their tax advisor and qualified intermediary review the specific ownership structure and transaction. [1][5]
A Useful First Step
Before listing or transferring investment property, ask a tax professional whether a 1031 exchange may fit your situation. Discuss the owner of record, how the property has been used, your goals for replacement property, likely timing, debt, and any entity or co-owner issues. Early planning matters because some exchange steps must happen before closing.
This article provides general information, not tax, legal, or investment advice. Section 1031 eligibility and tax treatment depend on the facts and current law. Consult your own CPA, tax attorney, and qualified exchange professionals before acting. Vorsa Investments does not represent that an investment it offers is eligible for 1031 exchange treatment.
These primary sources support the general federal tax explanations in the drafts. Review the current law, IRS publications, and transaction-specific facts with a qualified tax professional before relying on them.
1. Internal Revenue Code Section 1031 — https://uscode.house.gov/view.xhtml?req=%28title%3A26+section%3A1031%29
2. IRS Instructions for Form 8824 (2025) — https://www.irs.gov/instructions/i8824
3. IRS Publication 544, Sales and Other Dispositions of Assets (2025) — https://www.irs.gov/publications/p544
4. IRS About Form 8824, Like-Kind Exchanges — https://www.irs.gov/forms-pubs/about-form-8824
5. Treasury Regulation 1.1031(a)-3, Definition of Real Property — https://www.ecfr.gov/current/title-26/section-1.1031(a)-3
To subscribe to the newsletter, scan or click the QR code 👉